Asking rates across Mussafah and ICAD have moved noticeably over the past twelve months, driven less by new supply than by who is competing for existing space.
Where demand is coming from
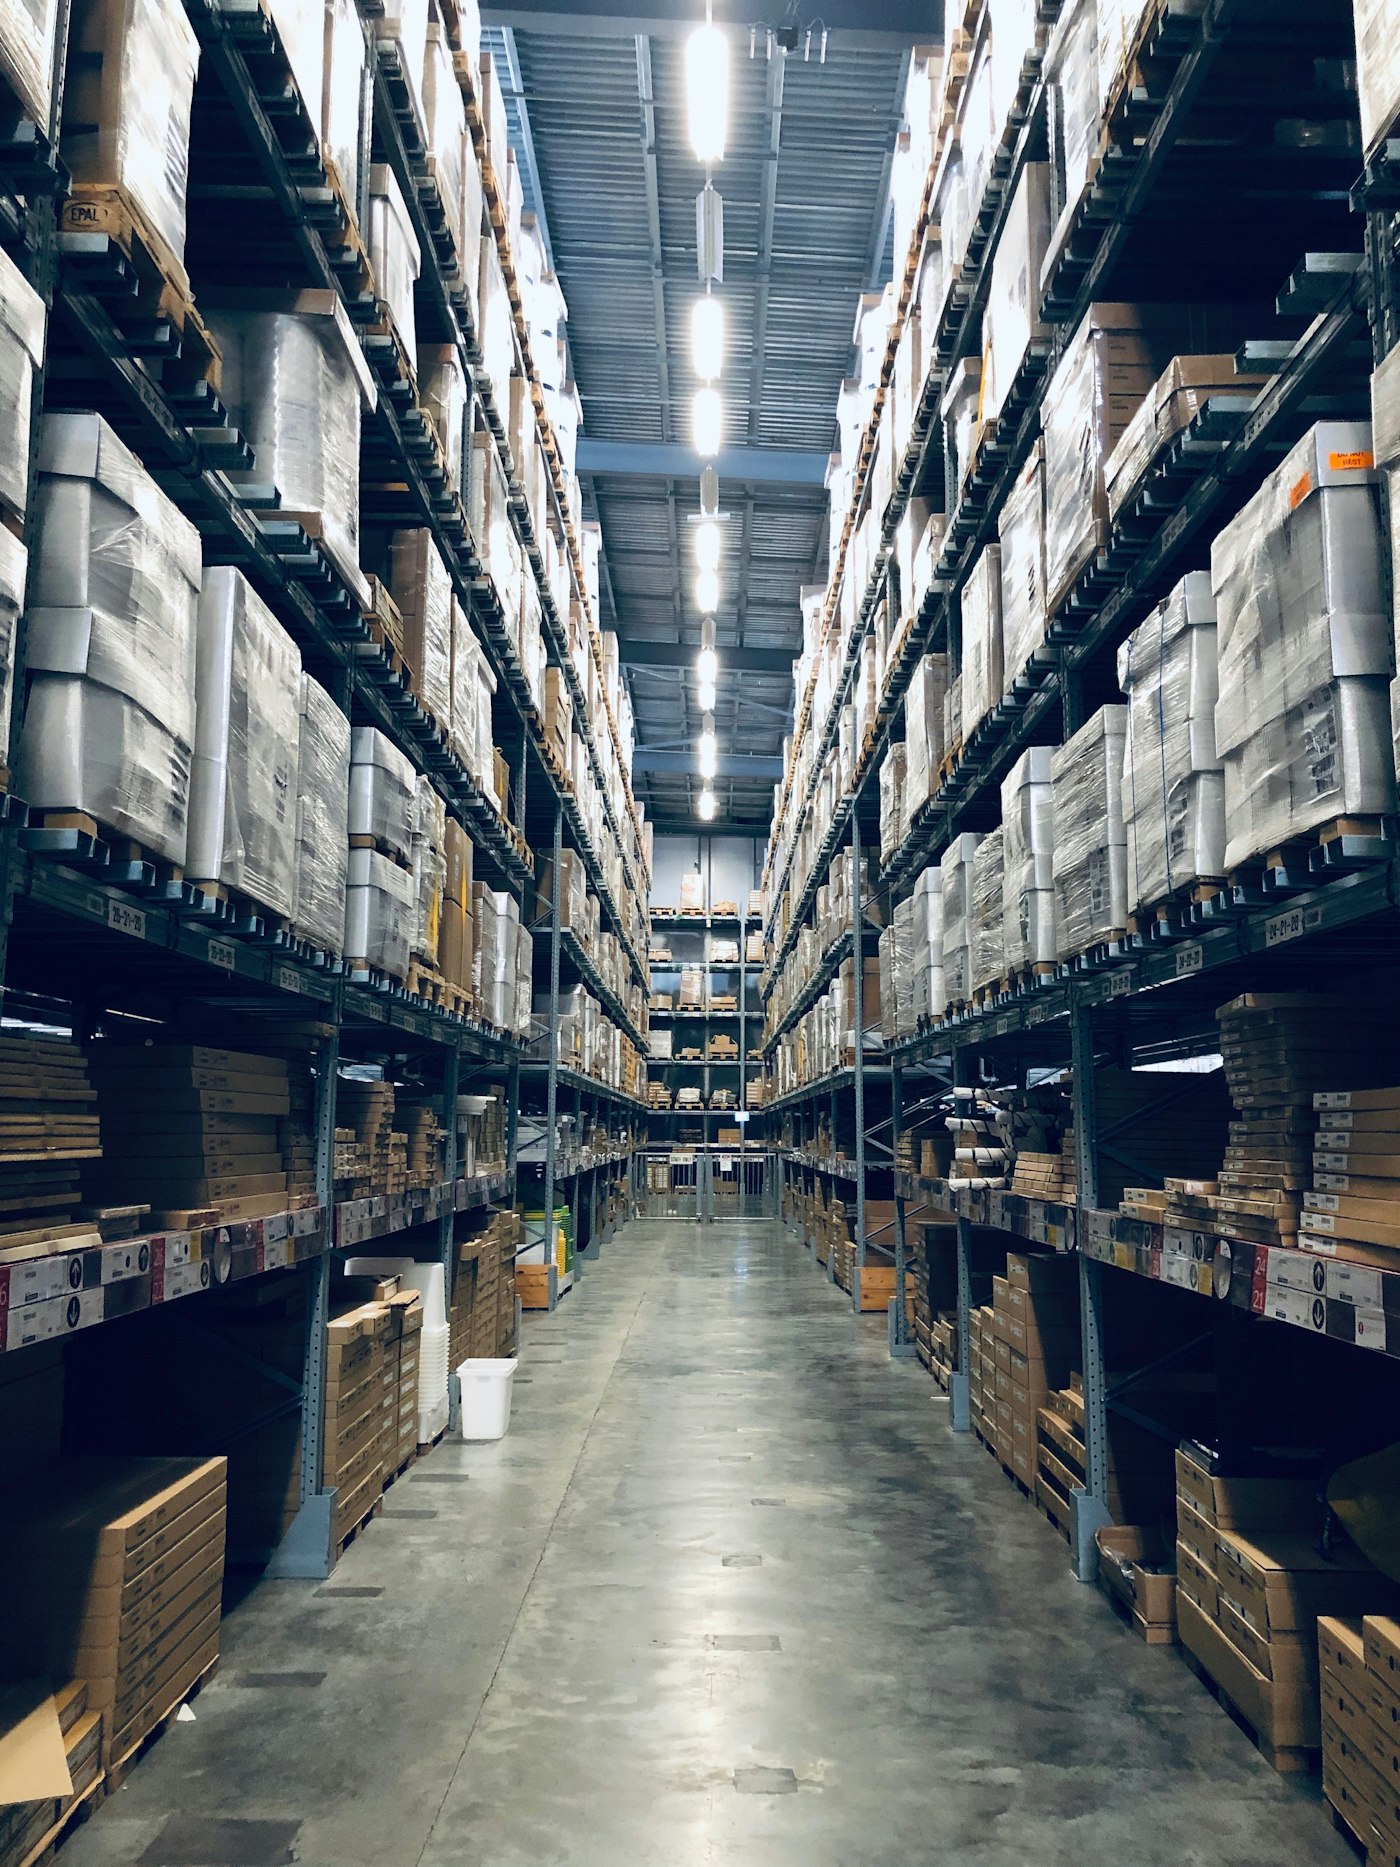
Logistics and last-mile distribution operators have been the most active tenants, absorbing mid-size units between 3,000 and 6,000 square feet. Light manufacturing has been steadier, with renewals outnumbering new lettings.
What that means for rates
Units with container-height shutters and integrated office space command a clear premium. Plain storage boxes without loading provision have held flat, and in some sub-zones softened slightly.
Where the value still is
The M-zones furthest from the E11 interchange remain the best value per square foot, particularly for operations that do not need daily container movements.


Join The Discussion